When you look for a used car loan in Pune, you will usually be offered two kinds of lenders: banks and NBFCs. Many buyers wonder which is better. The honest answer is that neither is better for everyone. The right choice depends on your income, credit profile, the car you are buying and how quickly you need the money. This guide explains the bank vs NBFC used car loan difference in simple terms, so you can choose with confidence.
What Is the Difference Between a Bank and an NBFC?
A bank accepts deposits from the public and offers a wide range of services, including loans. An NBFC (Non-Banking Financial Company) lends money but does not hold a banking licence. Both are regulated in India, and both can offer used car loans. In either case, the car you buy is generally the security for the loan, and the lender’s name is noted on the vehicle’s registration until you close the loan.
Bank vs NBFC Used Car Loan: Quick Comparison
| Factor | Banks | NBFCs |
|---|---|---|
| Interest rate | Often lower for applicants with a strong profile | Can be higher, depending on the profile and risk |
| Eligibility | Usually stricter on credit score and documents | Often more flexible on profiles and documents |
| Processing speed | Can be slower, depending on the bank | Often quicker, depending on the lender |
| Self-employed applicants | Considered, but documentation norms may be strict | Often more open to varied income proofs |
| Older used cars | May have tighter limits on car age | May consider a wider range, subject to policy |
| Existing customers | Existing relationship can help | Not dependent on a banking relationship |
These are general patterns, not rules. Every lender has its own policy, so individual cases can differ.
When a Bank May Suit You
- You have a strong credit score and a stable, well-documented income.
- You are buying a relatively newer used car that fits the bank’s criteria.
- Getting the lowest possible interest rate matters more to you than speed.
- You already hold a salary or savings account with the bank.
When an NBFC May Suit You
- You are self-employed or your income is harder to show through standard documents.
- Your credit profile is average or needs a closer look.
- You need faster processing, for example during a festive rush.
- The car is older or does not fit a bank’s limits.
If you fall into the self-employed category, see our guide on a self-employed car loan in Pune. If your credit score is a worry, read about a car loan with a low CIBIL score.
What to Compare Beyond the Interest Rate
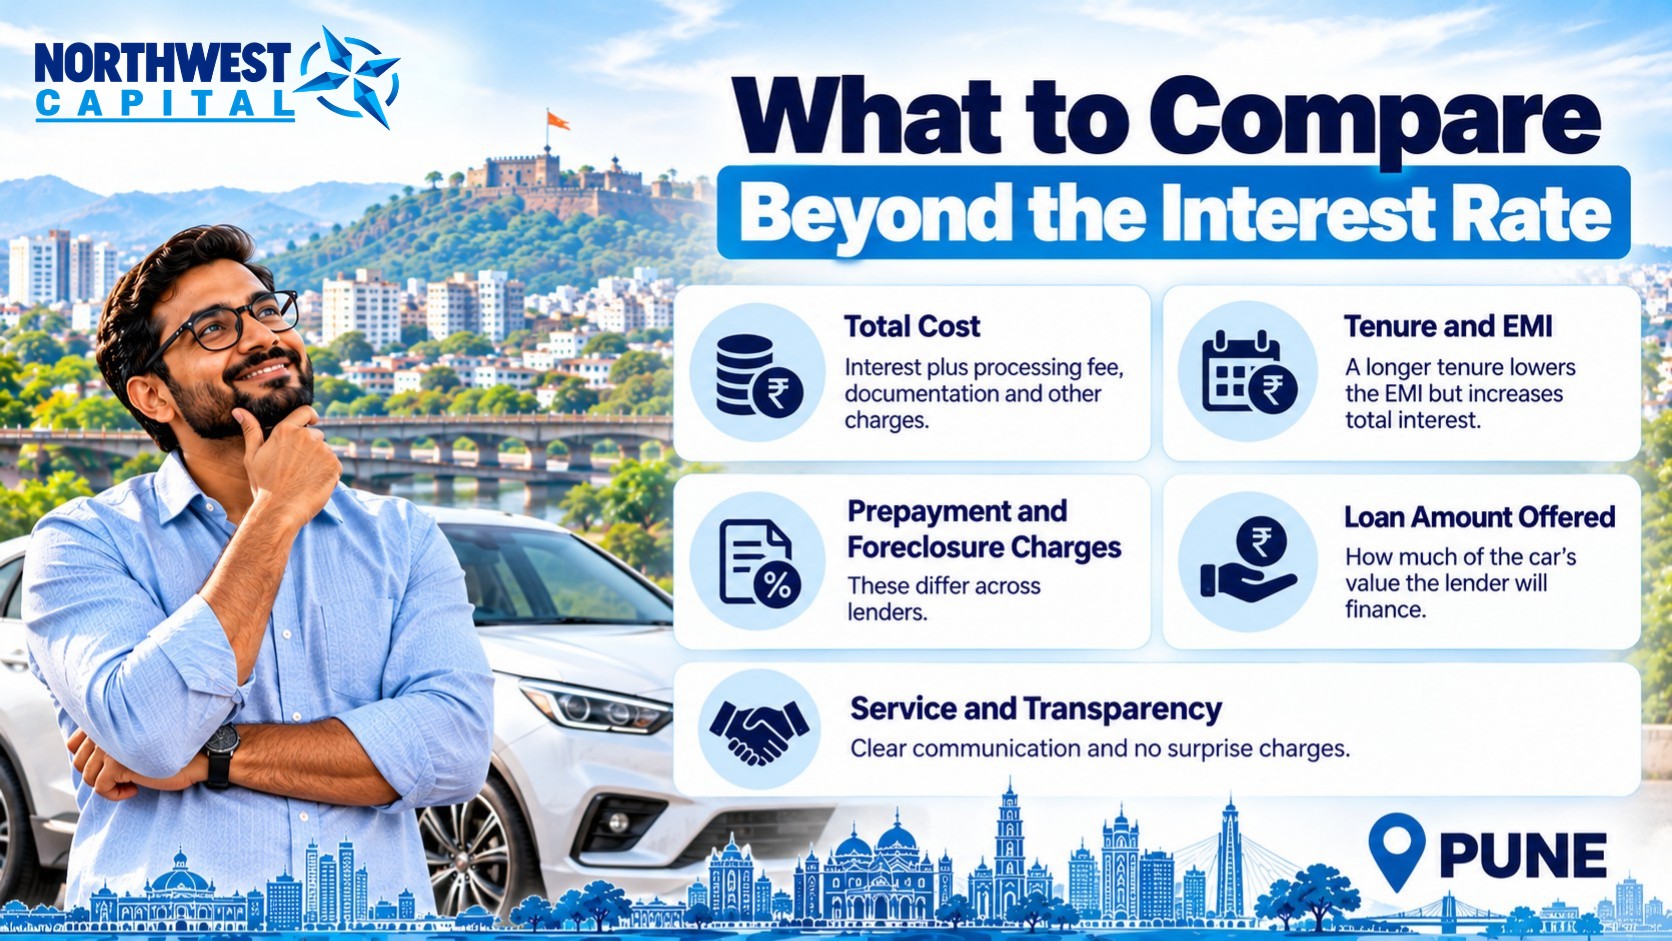
- Total cost: interest plus processing fee, documentation and other charges
- Tenure and EMI: a longer tenure lowers the EMI but increases total interest
- Prepayment and foreclosure charges: these differ across lenders
- Loan amount offered: how much of the car’s value the lender will finance
- Service and transparency: clear communication and no surprise charges
For a worked cost example, read our post on used car loan vs personal loan.
Safety Checks Before You Choose a Lender
- Confirm that an NBFC is registered with the Reserve Bank of India. The RBI publishes a list of registered NBFCs on its website.
- Be careful of anyone asking for money upfront before a loan is sanctioned.
- Do not trust promises of guaranteed approval.
- Read the sanction letter fully, including fees and charges, before signing.
Why Comparing Both Helps
Since banks and NBFCs follow different policies, a case that one lender is not comfortable with may suit another. Comparing across both types gives you a better chance of finding suitable terms. Applying to many lenders yourself can create multiple credit enquiries, so a guided process is often smoother.
How Northwest Capital Can Help
With 26+ years of experience and 50+ bank and NBFC partners, Northwest Capital helps eligible customers across Pune and Maharashtra compare options from both types of lenders and choose one that fits their profile. Learn more in our Used Car Loan in Pune & Maharashtra guide.
Frequently Asked Questions
1. Is a bank or an NBFC better for a used car loan?
Neither is better for everyone. Banks often suit strong, well-documented profiles, while NBFCs can be more flexible for other profiles. The right choice depends on your situation.
2. Are NBFC loans safe?
NBFCs registered with the RBI operate under its regulation. Always confirm registration and read the loan terms before signing.
3. Do NBFCs always charge higher interest?
Not always. Rates depend on the lender, your profile and the car. Compare the full cost, including fees, rather than the rate alone.
4. Can I switch lenders later?
Options like balance transfer may be available, but they depend on the lender’s terms and may involve charges. Check these before you take the loan.
5. Does Northwest Capital work with both banks and NBFCs?
Yes, we work with a network of bank and NBFC partners to help eligible customers across Pune and Maharashtra compare options.
Not sure whether a bank or an NBFC suits you? Talk to Northwest Capital and compare suitable options. Contact us to get started.
Disclaimer: This article is for general information only and is not a loan offer or a guarantee of approval. Eligibility, interest rates, fees and approval depend on the respective lender’s policies and the applicant’s profile.