Running your own business or practice does not mean you cannot get finance for a car. A self employed car loan in Pune is available to eligible business owners, professionals and traders. The difference is in how lenders assess your income. Salaried applicants show salary slips, while self-employed applicants usually need to prove a steady business income in other ways. This guide explains who is considered self-employed, what lenders look at, which documents you need, and how to improve your chances.
Who Is Considered Self-Employed for a Car Loan?
- Business owners and proprietors, including shop owners and manufacturers
- Partners in a firm and directors of private limited companies
- Professionals such as doctors, chartered accountants, lawyers, architects and consultants
- Traders, contractors, transporters and freelancers with a regular income
Why Lenders Treat Self-Employed Applicants Differently
Self-employed income can go up and down from month to month, unlike a fixed salary. Because of this, lenders look more closely at the business’s track record and financial documents. This does not mean approval is harder in every case. A well-documented, stable business can have a strong profile, sometimes stronger than a salaried applicant’s.
Self-Employed Car Loan Eligibility
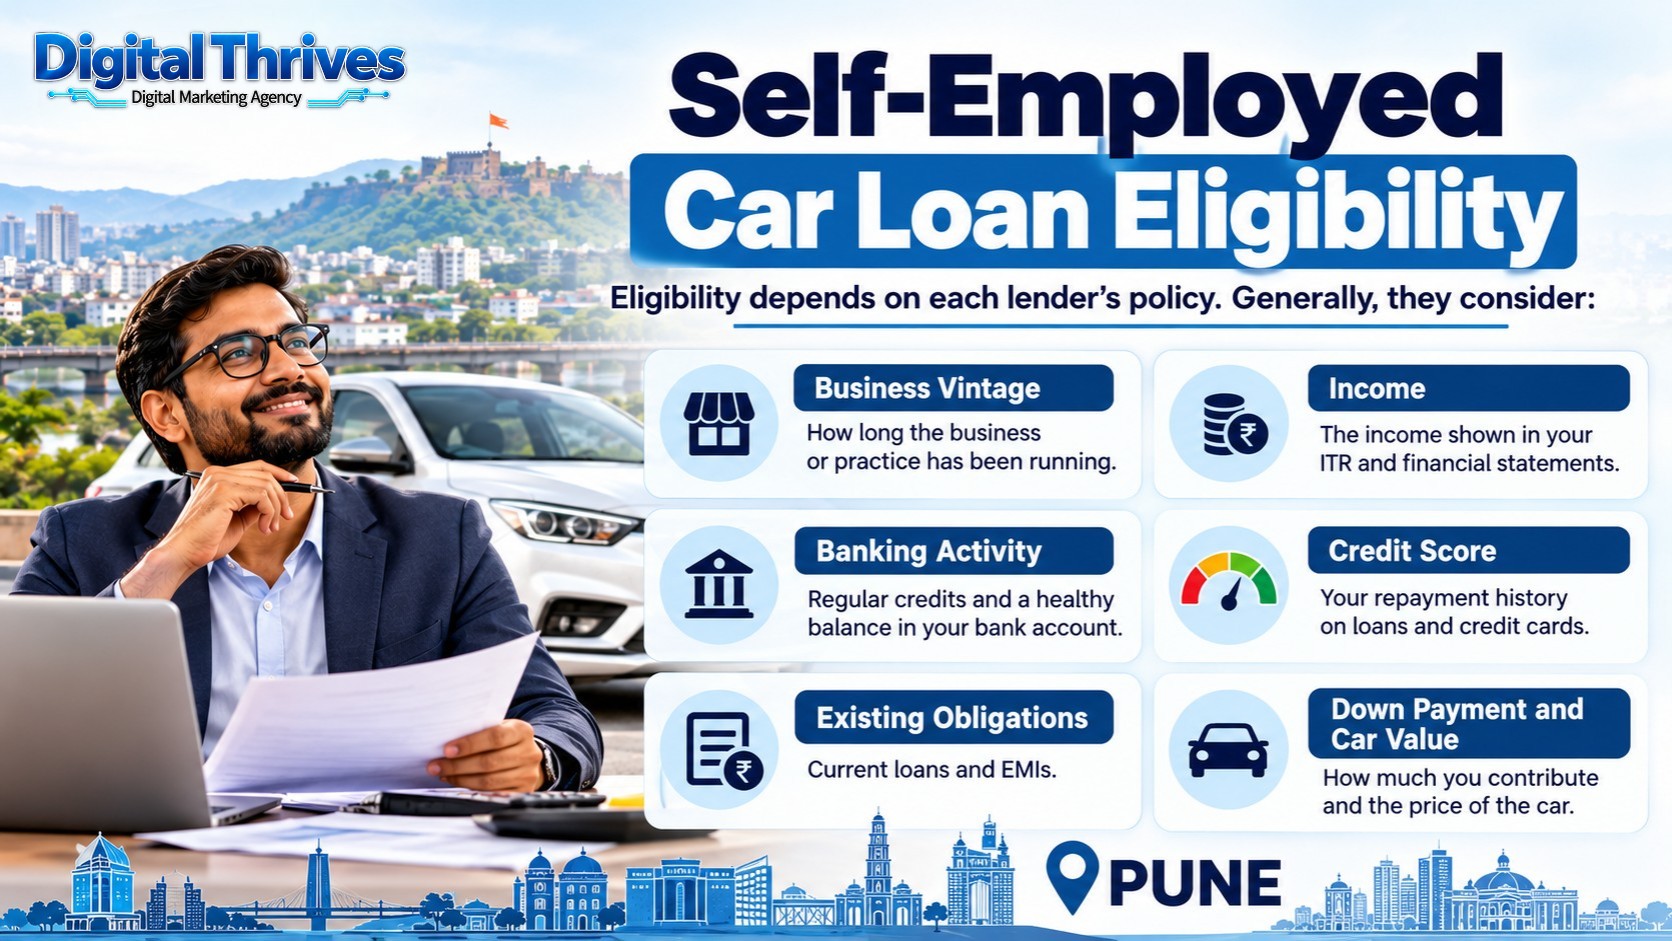
Eligibility depends on each lender’s policy. Generally, they consider:
- Business vintage: how long the business or practice has been running
- Income: the income shown in your ITR and financial statements
- Banking activity: regular credits and a healthy balance in your bank account
- Credit score: your repayment history on loans and credit cards
- Existing obligations: current loans and EMIs
- Down payment and car value: how much you contribute and the price of the car
Documents Required for a Self-Employed Car Loan
Identity and Address Proof
- Aadhaar Card and PAN Card
- Passport or Driving Licence, where applicable
Business Proof
- GST registration, Udyam registration, Shop Act licence or similar, as applicable
- Partnership deed or company documents, if relevant
- Professional registration certificate, for doctors, CAs and similar professionals
Income Documents
- Income Tax Returns (ITR) with computation of income. Lenders usually ask for recent years, and the number of years varies by lender.
- Bank statements, commonly for the last several months
- Profit and loss statement and balance sheet, where required
Vehicle Documents (for a used car)
RC, insurance and related papers of the car. The exact list differs between lenders, so confirm it before you apply.
How Lenders Assess Self-Employed Income
Some lenders mainly rely on the income shown in your ITR. Others place more weight on bank statements and your banking turnover. Because policies differ, an applicant who does not fit one lender’s method may fit another’s. This is one reason comparing several lenders is useful.
Tips to Improve Your Chances
- File your ITR regularly and on time, since it is a key proof of income.
- Route business income through your bank account to build a clear banking record.
- Keep business and personal transactions as organised as you can.
- Check your credit score before applying and fix any errors on your report.
- Make a reasonable down payment to reduce the loan amount.
- Keep EMIs on existing loans under control, as they affect your repayment capacity.
- Consider adding a co-applicant if your profile needs support, subject to the lender’s policy.
Common Reasons a Self-Employed Application Gets Declined
- Income shown in the ITR is low compared with the loan amount requested
- Irregular bank activity or low balances
- A short business history
- Low credit score or recent missed payments
- Incomplete or mismatched documents
If your credit score is a concern, read our guide on getting a car loan with a low CIBIL score.
New Car, Used Car or Refinance: Which Fits You?
Self-employed applicants can explore all three routes. A New Car Loan suits a fresh purchase, while a Used Car Loan can keep the loan amount lower. If you already own a car and need funds for business needs such as working capital, Car Refinance may be worth exploring.
How Northwest Capital Can Help
With 26+ years of experience and 50+ bank and NBFC partners, Northwest Capital helps eligible self-employed customers across Pune and Maharashtra understand which lenders may suit their profile, organise their documents and move through the process with dedicated support.
Frequently Asked Questions
1. Can a self-employed person get a car loan in Pune?
Yes. Eligible self-employed applicants can explore car loans based on their business income, documents and credit profile, subject to the lender’s policy.
2. Is ITR compulsory for a self-employed car loan?
Many lenders ask for ITR as the main income proof. Some also consider bank statements. Requirements vary by lender, so check before applying.
3. How long should my business have been running?
Lenders usually prefer an established business, but the required period differs from one lender to another.
4. Can professionals like doctors and CAs apply?
Yes. Eligible professionals can apply with their registration proof and income documents.
5. Does the car have to be bought in my name or my company’s name?
This depends on the lender’s policy and how you plan to use the car. Discuss your situation with your loan consultant before applying.
Self-employed and planning to buy a car? Talk to Northwest Capital to understand your options before you apply. Contact us to get started.
Disclaimer: This article is for general information only and is not a loan offer or a guarantee of approval. Eligibility, interest rates, fees, required documents and approval depend on the respective lender’s policies and the applicant’s profile.